Your Local Mortgage Lender
Located in Greenwood Village, Colorado
Personalized Mortgage Experience
Brock Walker offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Greenwood Village, Colorado.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
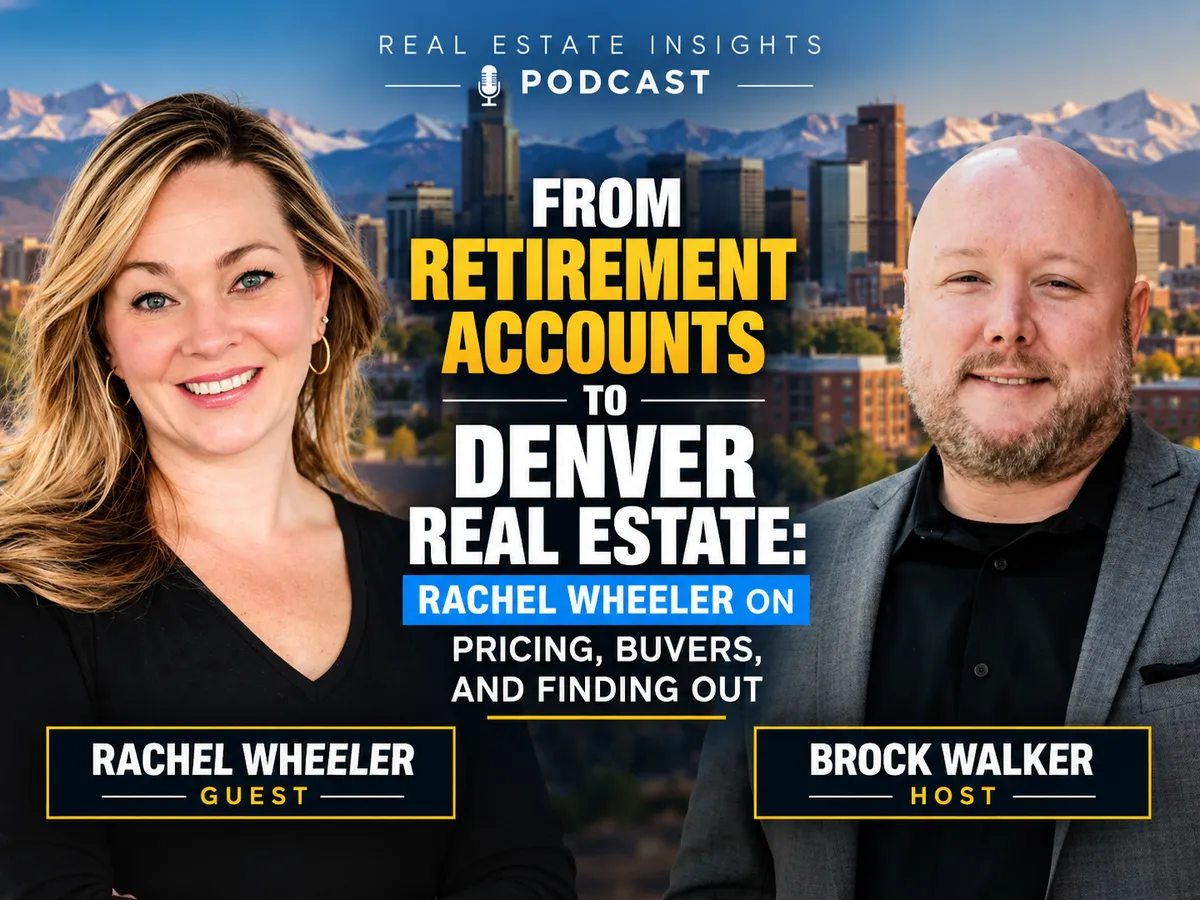
Colorado Real Estate Spotlight: Brock Walker Talks Denver Market and Client Education With Rachel Wheeler of KM Luxury Homes
The Retirement Account Expert Who Became One of Denver’s Most Educated Realtors
Brock Walker welcomed Rachel Wheeler of KM Luxury Homes to the Colorado Real Estate Spotlight podcast for a conversation that covers more ground than most real estate interviews. Rachel has spent more than two decades in the real estate industry before becoming a licensed realtor six years ago. Her pre-licensure career involved helping clients navigate IRS guidelines to use retirement accounts to invest in real estate across all fifty states. She has seen more purchase and sale documents, property tax structures, and state-specific closing processes than most agents encounter in a lifetime of transactions. That background shapes every conversation she has with buyers and sellers in the Denver metro today.
KM Luxury Homes is a boutique woman-owned brokerage in Denver where Rachel has been since close to the beginning. KM stands for Kelly Martin, the managing broker, and the team of approximately twenty agents operates with the kind of collaborative accessibility that Rachel credits with making her a better resource for her clients.
How Twenty States of Real Estate Experience Became One Agent’s Competitive Advantage
When Rachel worked as a supervisor and manager at First Trust Company overseeing real estate investments she was reviewing transactions across every state in the country. Every state has different terminology. Different processes. Different paperwork requirements. Some states do not use title companies at all and close exclusively through attorneys. That exposure produced a working knowledge of how real estate transactions actually function at their structural level that most agents who only practice in one state never develop.
She is careful to clarify that her Colorado license means she only practices here. But the depth of process knowledge she brings to every Colorado transaction is significantly broader than what six years of local practice alone would produce.
What Growing Up in Westminster Has Given Her Clients
Rachel grew up in Westminster and has watched the area transform over decades. That local depth shows up in how confidently she can speak to the history, the schools, the neighborhoods, and the growth trajectory of the areas where her clients are looking. For buyers relocating from outside Colorado or outside the Denver metro that kind of grounded local knowledge is genuinely hard to replicate with research alone. She can tell the story of Westminster in a way that helps buyers understand not just what is there now but where it came from and where it is going.
Why She Stops the Noise Before Anything Else
One of Rachel’s most consistent practices in client conversations is what she calls stopping the noise. Buyers come in having absorbed national headlines about interest rates, affordability, and the impossibility of owning in Colorado. That noise has become a shared narrative that people repeat to each other without examining whether it actually applies to their specific situation.
When she overhears someone say they can never afford a home in Colorado her instinct is to pull them aside and ask what they actually want. Then refer them to a lender and find out what is actually possible for their specific income, savings, and goals before accepting the conclusion that the news gave them. In most cases the gap between what people assume and what is actually achievable is significant.
Her direct advice for buyers who are waiting for rates to improve is equally clear. Waiting for things to get cheaper is not a reliable strategy in any market and certainly not in Colorado real estate. If you are financially ready the right move is to lock in what is available now, accept the current rate for what it is, and know that refinancing is an option when conditions change. You cannot go back and buy at today’s price after waiting a year for a more comfortable environment that may or may not arrive.
The Opportunity She Thinks Buyers Are Missing
New construction. Rachel sees buyers overlooking builder inventory and the incentives attached to it. Whether working with a builder’s preferred lender or bringing existing lender relationships to the table to negotiate comparable terms new construction often represents a more accessible entry point than buyers realize. The incentive packages available in the current market from builders who are motivated to move inventory are real and they are worth exploring before dismissing new construction in favor of resale.
How She Works With Clients From Start to Finish
Rachel’s approach to a client relationship starts with understanding what is actually happening in their life and what is motivating the transaction. The motivation behind the desire to buy or sell shapes everything about how she advises and what she prioritizes.
From there she focuses heavily on education. Not the kind of education that overwhelms with process detail but the kind that removes fear and replaces it with clarity. Real estate transactions are stressful at times. They do not have to be scary. Rachel’s job is to make sure clients understand what is happening at every stage, why it is happening, and what comes next so nothing arrives as a surprise.
She is also explicit about what she is not. She is not a roofer, not an appraiser, not a structural engineer. Her investment background trained her to give options and information within her expertise and refer everything else to the right specialist. That discipline around staying in her lane while being genuinely knowledgeable about the lane she is in is one of the most consistent things her clients experience working with her.
She handles her own paperwork and does not use a transaction coordinator because she deliberately keeps her transaction volume at a level where she can be fully present for every client. Not volume for its own sake but quality and focus.
Her Number One Thing That Sellers Need to Hear
Price the home right. Rachel is emphatic about this and direct about what happens when sellers do not. Homes priced correctly in the Denver market move quickly even in a slower environment. The ones sitting on the market are almost universally overpriced. Watch the price reductions on any sitting listing and you will see exactly what happens. Down, down, down until the market eventually tells the seller what it was willing to pay from the beginning, except now the listing is stale and the perception of something being wrong with the property has had time to develop.
She would not take a listing at a price she could not support with the comps. That conviction protects both her clients and her professional integrity and she considers it the most fundamental thing she does differently from agents who chase listings at inflated prices and then fight the market for months.
What She Does When She Is Not Helping Clients
Rachel stays current through continuing education on topics outside the core curriculum including septic systems, well water, mountain properties, and divorce situations. Not because she wants to be an expert in every specialty but because having general working knowledge makes her a better resource when those situations arise.
She organizes social events for her sphere including a headshots day that helped clients and contacts update their LinkedIn and social media photos. Nothing transactional. Just genuine relationship building that keeps her connected to people who will think of her when real estate questions come up.
She plays in two Bunko groups. Her daughter Carmen just graduated from Colorado State with an interior architecture and design degree and holds her real estate license, which Rachel expects will fit naturally into her career going forward.
Rachel’s Closing Message for Anyone Thinking About Buying or Selling
Find out. That is her son’s high school football team’s slogan for the year and it applies perfectly. Stop absorbing the doom and gloom of national news coverage and YouTube commentary about real estate. The only thing that matters is your particular situation. Pick up the phone, call a lender, call a realtor, and find out what is actually possible for you right now. If today is not the day that is fine. At least you have a starting point and a plan instead of a fear based on someone else’s narrative.
How to Reach Rachel Wheeler
Call or text 720-838-4648. Email [email protected]. Find her on Instagram and Facebook at Bliss Homes. She serves buyers and sellers throughout the Denver metro including Westminster and the surrounding suburbs at KM Luxury Homes.
Brock Walker is available for mortgage financing conversations across Colorado. Reach out to Brock Walker to connect on the lending side of any transaction Rachel is working and to find out what is actually possible for your specific situation in the Colorado market.
Sources
ColoradoAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
